Mortgage Crisis Hurts Black, Latino Economic Progress
by James Parks
This article originally appeared in AFL-CIO Blog.
"The subprime crisis has pulled a large chunk of wealth
away from many, many middle- and lower-income people."

Not only has the nation's slumping economy hit black
workers and Latino
workers hard, the mortgage
crisis has had a disproportionate impact on them as well. In fact, some
experts fear the mortgage crisis could undo a huge portion of the wealth built
up by the growing African American and Latino middle classes.
The Joint Center for
Political and Economic Studies reports that the rate of subprime mortgages
for Latinos and African Americans is about double the rate for whites. In 2006,
subprimes made up one in four mortgages (26 percent) made to whites, 47 percent
of those to Latinos and 53 percent of mortgages that went to African Americans.
At a recent forum sponsored by the Economic Policy Institute
EPI) and its Agenda for Shared Prosperity,
Wilhelmina Leigh of the Joint Center said the legacy of discrimination against
people of color combined with a recent federal push for higher homeownership
rates created the opportunity for predatory subprime lenders to prey on people
of color.
"One in 12 home loans made to Latinos in recent years will
end in foreclosure."
Graciela Aponte of the National
Council of La Raza, a former housing counselor, recalls ads in
Spanish-language newspapers that promised zero-down, 1 percent mortgages and
other exotic vehicles that paid high commissions to the brokers who pushed
them. She estimates that one in 12 home loans made to Latinos in recent years
will end in foreclosure.
EPI economist Algernon Austin,
who heads the institute's Race, Ethnicity and the Economy program, says in a study
released last week that creditworthiness-alone or in combination with factors
other than race-cannot account for the disparities in subprime loan rates. When
the Federal Reserve and the Wharton School of Business conducted an analysis
that took into account how many adults in a neighborhood were high-credit
risks, they still found a link between the amount of subprime loans and the
number of minorities in the neighborhood. An analysis by the Center for Responsible Lending
found that even after taking into account individual credit scores, Latino and
African American borrowers were more than 30 percent more likely to receive
higher-rate subprime loans.
Meanwhile, a startling new
report has predicted the subprime mortgage crisis will cause people of color to
lose up to $213 billion, leading to the greatest loss of wealth in modern U.S.
history. The report, Foreclosed: State
of the Dream 2008, by United for
a Fair Economy, accuses mortgage lenders of deliberately targeting the poor
and people of color with high-cost loans.
According to the
report:
"The spillover effect from the
wholesale writing of bad loans is that communities are torn apart. As one house
after another in a neighborhood goes vacant, squatters move in, crime and the
likelihood of fires spike, local stores and businesses close. The value of the
houses other people in the vicinity, who have not taken out subprime loans,
live in deteriorates by thousands of dollars. The subprime crisis has pulled a
large chunk of wealth away from many, many middle- and lower-income people, in
the form of homes and home equity - a primary, even sole, asset for those
without great wealth. The government has remained silent and inactive."
The AFL-CIO
Executive Council in March outlined several steps to address the mortgage
crisis, including a six- to 12-month
moratorium on mortgage foreclosures and changes in bankruptcy laws to allow
mortgages to be modified so families can keep their homes. The council
also called for an end to servicing agreements that reward mortgage companies
for foreclosing on homes rather than encouraging refinancing or other workout
strategies and supported strong new rules for the mortgage and financial
markets that hold the industry accountable.

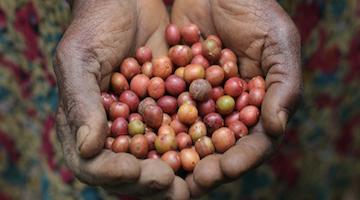 Food production in Africa is complicated by climate change and the use of fertilizers which increase food production but which also create green house gases and create other environmental harm.
 …
 Onyesonwu Chatoyer of the All-African People's Revolutionary Party and BAR Book Forum Editor Roberto Sirvent discuss how "We Can Save Ourselves."
 This week’s featured scholar is Ayodeji Ogunnaike. Ogunnaike is an assistant professor at Bowdoin College where he teaches interdisciplinary courses on Africa and the African Diaspora highlighting…
 The electoral system alone doesn't bring about change that benefits the people. People-centered political formations must be part of any political process.